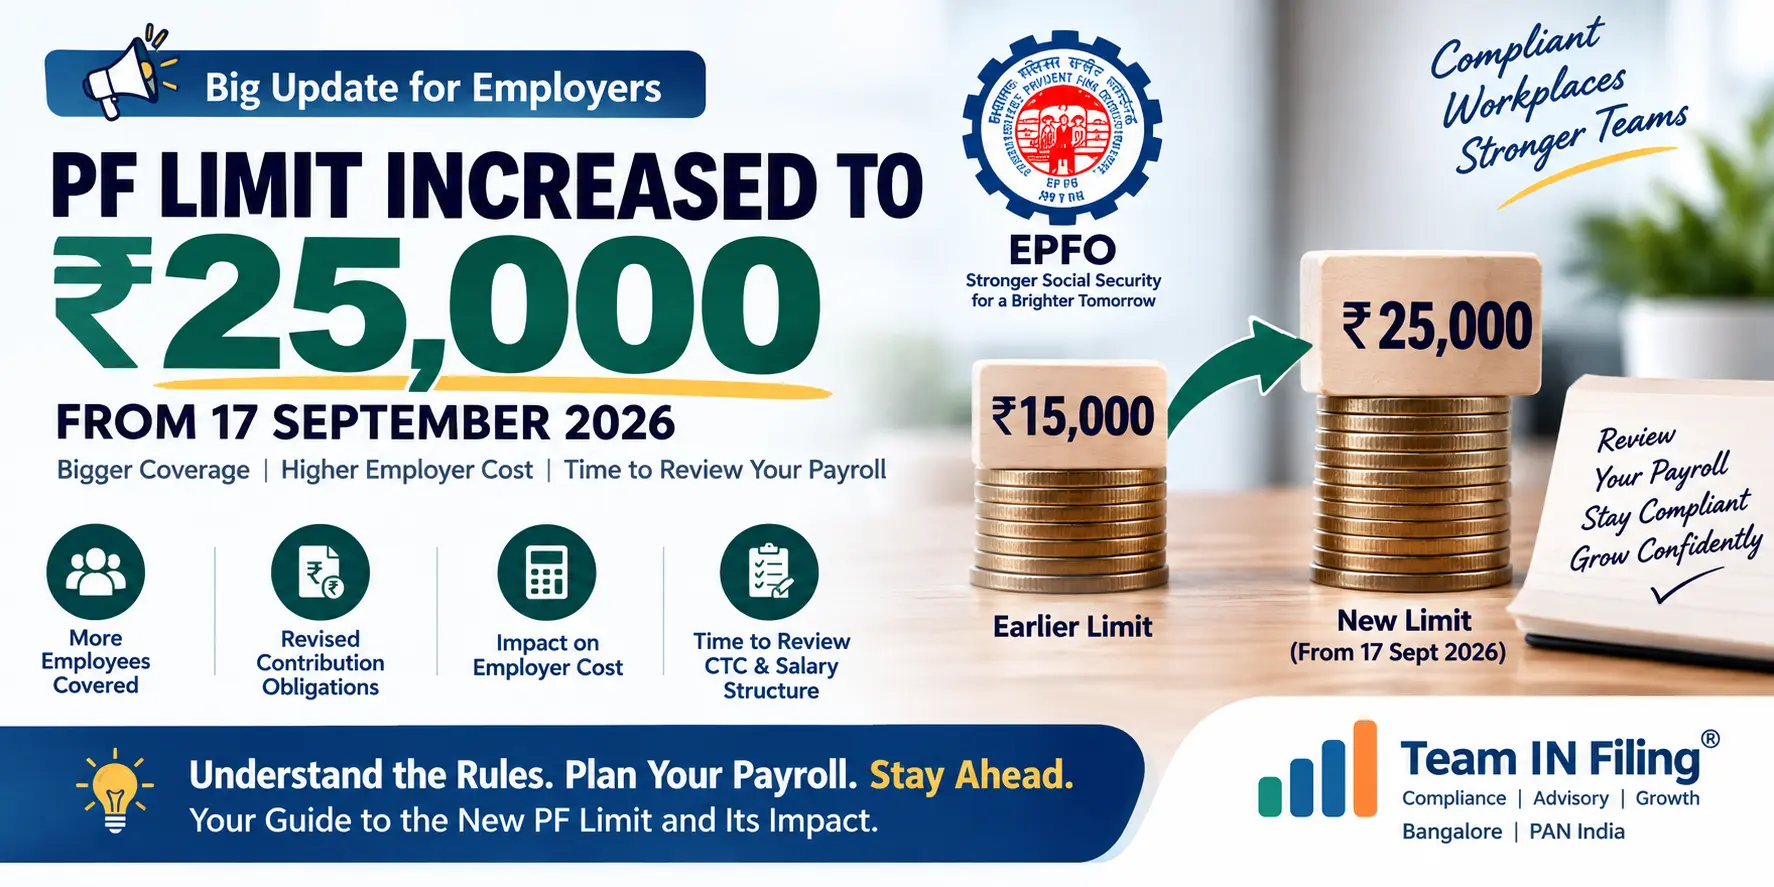
Major PF change from 17 Sept 2026: The EPFO statutory wage ceiling for mandatory coverage has increased from ₹15,000 to ₹25,000 per month. But employers should not look at this change in isolation. The real payroll impact comes from reading the new PF ceiling together with the Labour Code’s 50% wage principle, because the way an employee’s remuneration is structured can determine the statutory wage base on which social-security benefits and contributions are considered.
This is why the latest PF notification is much more important than simply changing a number from ₹15,000 to ₹25,000 in payroll software. A company may have an employee with a monthly CTC of ₹30,000, ₹40,000, ₹50,000 or more, but the relevant statutory wage cannot be decided merely by looking at the employee’s CTC figure. The employer has to first examine the employee’s remuneration under the applicable definition of “wages” and then determine the PF treatment under the Social Security Code and applicable EPFO provisions.
The Labour Codes have introduced a more standardised approach to determining wages for statutory benefits. Broadly, wages include basic pay, dearness allowance and retaining allowance, while certain excluded components are subject to the 50% rule. Where the specified excluded components exceed the permitted proportion of total remuneration, the excess is brought back into wages for statutory calculations. The Ministry of Labour & Employment’s own clarification explains that this wage-definition mechanism is relevant for calculating social-security benefits and contributions.
Now place the new PF rule alongside that rule. On 17 Sept 2026, the Government notified ₹25,000 per month as the PF Limit increased for the purposes of Chapter III of the Code on Social Security, 2020, replacing the earlier ₹15,000 ceiling. The Gazette notification makes the change effective from the date of its publication in the Official Gazette.
The important point for employers: ₹25,000 is the revised EPFO wage ceiling for mandatory coverage. It should not be confused with a rule that every employee’s PF wage automatically becomes ₹25,000. The employee’s statutory wage must first be determined under the applicable wage definition and then the relevant PF ceiling and contribution provisions must be applied.
Consider why the 50% wage principle matters. If an employee’s total remuneration is ₹30,000 per month and the applicable wage calculation results in ₹15,000, the employee may sit exactly around the old PF ceiling. If another employee has ₹50,000 of total remuneration and the statutory wage calculation results in ₹25,000, the new PF ceiling becomes directly relevant. The actual position, however, depends on the employee’s wage components and the applicable statutory and scheme provisions — it cannot be decided merely by applying a flat 50% formula to every CTC.
This distinction becomes particularly important for employers who historically kept basic salary relatively low and a large portion of remuneration under allowances. Under the Labour Code wage framework, simply changing the labels of salary components does not necessarily keep those amounts outside the statutory wage calculation. Where the prescribed threshold is crossed, the relevant excess may have to be added back into wages.
Therefore, the September 2026 PF change creates a practical compensation question for management: Are our existing salary structures still correctly designed under the current wage and social-security framework? If the answer is unclear, the company should review the employee-wise salary breakup before simply increasing PF deductions in the payroll system.
The financial impact can be significant. When an employee comes within the revised mandatory coverage framework, the employee’s statutory contribution can affect take-home salary, while the employer’s corresponding contribution can increase the company’s cost of employment. Recent reporting on the new ceiling illustrates the potential change for employees who were previously capped at ₹15,000, but the actual impact varies depending on whether the employer already contributes on actual wages, the employee’s PF membership position and the applicable wage base.
This is precisely where a Bangalore labour-law and PF consultant should look beyond the ECR filing. The objective is not to find a shortcut to avoid PF. It is to examine whether the company’s basic pay, allowances, statutory benefits and overall CTC structure are properly designed under the current Labour Code framework, while ensuring that the revised EPFO ceiling is correctly applied.
What Team IN Filing checks: We can review the employee-wise CTC and salary structure, identify the components that form part of the statutory wage calculation, examine the impact of the 50% wage principle, determine which employees are affected by the revised ₹25,000 EPFO ceiling, and calculate the likely employer-cost and employee-take-home impact before the payroll and ECR are finalised.
For an employer, this is the real significance of the September 2026 change. The question is not merely whether PF has increased from ₹15,000 to ₹25,000. The question is whether the company’s entire compensation structure now needs to be reviewed so that the business remains compliant with the Social Security Code, the wage-definition framework and PF requirements, without creating an unnecessary employment-cost burden through poor salary structuring.
Primary Government Source: Ministry of Labour & Employment, Government of India — Gazette Notification S.O. 5109(E), dated 17 September 2026. The notification specifies ₹25,000 per month as the wage ceiling for the purposes of Chapter III of the Code on Social Security, 2020.
View the Government Gazette Notification – PF Increased Increased to ₹25,000
The real question for employers: “Will my payroll cost increase, and will my employee’s take-home salary reduce?” The answer depends on the employee’s statutory wage, PF membership and existing contribution pattern — not simply on the employee’s CTC.
The increase from ₹15,000 to ₹25,000 creates a new review point for payroll teams. Employees who were previously outside mandatory coverage because their relevant wages exceeded ₹15,000 but were within the new ₹25,000 ceiling may now need to be examined for mandatory EPFO coverage under the revised framework.
A simple example
| Particular | Earlier ceiling | Revised ceiling |
|---|---|---|
| PF wage ceiling | ₹15,000 | ₹25,000 |
| Difference in ceiling | — | ₹10,000 |
The important point is that the ₹10,000 difference is not automatically the contribution amount. It is the increase in the notified wage ceiling. The actual PF contribution must be worked out after determining the employee’s applicable wage and the contribution provisions applicable to that employee.
Why the employer should calculate this employee-wise
Suppose a company has 25 employees who fall into the newly affected category. Even a modest increase in statutory employer contribution per employee can become a recurring monthly expense. Over 12 months, the impact becomes a genuine annual employment-cost question.
At the same time, the employee side cannot be ignored. Where the employee contribution increases, the employee may see a corresponding reduction in monthly take-home pay, although the amount is going towards statutory social-security benefits rather than disappearing from the employee’s compensation.
Employer’s calculation should therefore have two columns:
Company impact → additional statutory employment cost
Employee impact → change in monthly take-home pay
But there is another important layer: the 50% wage principle
The PF ceiling cannot be examined separately from the wage structure. Under the Labour Code framework, the statutory definition of wages and the 50% mechanism for excluded components can affect the wage figure used for social-security calculations. This means an employer should first determine the legally relevant wage and only then apply the PF ceiling.
For this reason, simply reducing Basic Pay and increasing allowances may not produce the result that an employer expects. Where the applicable excluded components cross the prescribed threshold, the excess can be brought back into wages for statutory calculations. A compensation structure should therefore be reviewed for its legal substance, not merely its salary labels.
Can an employer legally reduce the additional PF cost?
Cost planning is possible; artificial PF avoidance is not the objective. An employer can review whether its CTC and salary components are properly structured under the applicable wage and social-security rules. But changing labels merely to keep statutory wages artificially low can create a compliance problem rather than solve one.
This is where a professional PF and labour-law review adds value. Instead of changing Basic Pay mechanically, Team IN Filing can examine the existing compensation structure, identify the statutory wage components, calculate the employee and employer impact and then discuss a compliant restructuring approach.
Our practical approach: First calculate the legal wage. Then calculate PF. Then examine the CTC. Only after these three steps should a company decide whether its compensation structure needs modification.
For a Bangalore employer, this exercise can be particularly useful before the next payroll cycle. A small correction in the salary structure made before payroll and ECR filing is far easier to manage than correcting multiple months of payroll after a statutory query.
The practical change for employers: Earlier, the statutory EPF wage ceiling for mandatory coverage was ₹15,000 per month. From 17 September 2026, that ceiling has moved to ₹25,000. This means a wider group of employees can now fall within mandatory PF coverage, increasing the compliance and contribution responsibility of employers.
For a company already operating PF through its payroll, the change should be viewed employee-by-employee. If an employee’s applicable statutory wages were above the earlier ₹15,000 ceiling but are within the revised ₹25,000 ceiling, the employee’s PF eligibility now needs to be reviewed under the revised framework. The Government has specifically stated that the increase is expected to bring more than 51 lakh additional employees within mandatory EPFO coverage.
Where does the 50% wage rule come in?
This is the part many employers may miss. The PF ceiling and the Labour Code’s 50% wage principle have to be considered together. Basic Pay and Dearness Allowance form part of wages, while specified allowances and other excluded components are subject to the 50% mechanism. If the relevant excluded components exceed the permitted 50% of remuneration, the excess is added back to wages for statutory purposes. The Ministry of Labour & Employment has expressly clarified this mechanism. :
Simple way to understand it:
First determine the employee’s legally relevant wages under the applicable Labour Code rules.
Then check whether those wages fall within the revised ₹25,000 PF ceiling for mandatory coverage.
Then calculate the applicable PF contribution.
For example, an employee may have a monthly CTC of ₹30,000, ₹40,000 or ₹50,000. The employer should not automatically assume that PF wages are exactly 50% of CTC. The wage definition, included components, excluded components and the 50% add-back mechanism must first be examined. The Ministry itself gives an illustration where excess allowances are added back to Basic Pay and DA to arrive at the statutory wage figure.
Why this can increase company payroll cost
The important business impact is coverage expansion. Employees who were previously outside mandatory EPF coverage because of the old ₹15,000 ceiling may now come within the revised ceiling. Once an employee becomes subject to mandatory coverage under the applicable provisions, the employer must account for the corresponding statutory contribution and payroll compliance.
That means the additional cost should not be looked at as a one-time expense. For a company with several affected employees, the increase in monthly employer contribution can become a recurring annual payroll cost. At the same time, the employee’s contribution can affect monthly take-home salary, while increasing the employee’s PF savings and associated social-security benefits.
This is where salary structure becomes important
A company cannot solve the issue simply by changing the salary label from Basic Pay to Allowance. If the excluded components cross the statutory threshold, the excess can be added back into wages. Therefore, compensation restructuring has to be based on the actual legal character of the payment, not merely its name in the salary slip.
Our role as a PF and labour-law consultant in Bangalore is therefore broader than monthly ECR filing. We review the CTC structure, identify the relevant wage components, check the 50% mechanism, identify employees affected by the revised ₹25,000 ceiling and calculate the potential employer-cost and employee-take-home impact before recommending any restructuring.
Employer checklist: Don’t simply change ₹15,000 to ₹25,000 in payroll. Recalculate the statutory wage → identify newly covered employees → calculate PF → assess employer cost → check employee take-home → verify ECR.
The Government’s own implementation communication recognises that employers need to understand the revised contribution obligations arising from the enhanced wage ceiling. For companies, this makes the September 2026 change both a PF compliance issue and a compensation-planning issue.
The biggest confusion after the ₹25,000 PF ceiling is this: “If my employee earns ₹40,000 or ₹50,000, do I now calculate PF on ₹25,000?” Not automatically. The employer must first determine the employee’s statutory wages under the applicable Labour Code provisions, including the 50% mechanism, and then apply the PF coverage and contribution rules.
| Monthly CTC | What employer should check |
|---|---|
| ₹30,000 | Whether statutory wages reach the revised PF ceiling |
| ₹40,000 | 50% wage mechanism + PF eligibility + existing membership |
| ₹50,000 | Actual statutory wage, applicable ceiling and contribution treatment |
The key point: ₹30,000 CTC does not automatically mean ₹15,000 PF wages, and ₹50,000 CTC does not automatically mean ₹25,000 PF wages. The salary components must be examined under the applicable wage definition. The 50% mechanism can bring the excess of specified excluded components back into wages where the statutory conditions are met.
For employers: Do not redesign Basic Pay merely to keep PF low. First calculate the legally relevant wage, then determine PF. A properly structured CTC can manage employment cost while remaining compliant; artificial salary splitting can create future labour-law exposure.
At Team IN Filing, Bangalore, we can prepare an employee-wise PF impact sheet showing current CTC → statutory wages → PF eligibility → employer contribution → employee deduction → revised take-home. This gives management the actual financial impact before changing the payroll structure.
The easiest way to understand the financial impact is to look at an employee whose applicable PF wage moves from the old ₹15,000 ceiling to the revised ₹25,000 ceiling. The difference in the wage ceiling is ₹10,000 per month.
| Illustration | ₹15,000 | ₹25,000 |
|---|---|---|
| PF wage considered | ₹15,000 | ₹25,000 |
| Difference | — | ₹10,000 |
At a 12% contribution rate, ₹10,000 of additional PF wage would mathematically represent ₹1,200 additional employee contribution and ₹1,200 employer contribution per month, before considering the applicable allocation and other statutory provisions. Therefore, for an employee actually affected by the revised contribution base, the employer-side difference could be approximately ₹1,200 per month or ₹14,400 per year.
Important: This is only an illustration of the financial effect of a ₹15,000-to-₹25,000 PF wage increase. It does not mean every employee will have PF calculated on ₹25,000. The actual contribution depends on the employee’s applicable statutory wage, PF membership and the provisions governing the contribution.
For a company with 50 employees actually affected in this manner, the illustrative additional employer contribution could be around ₹60,000 per month, or ₹7.20 lakh annually. This is why the new PF ceiling deserves attention from management, not only from the payroll executive.
The employee also sees an impact: an illustrative additional ₹1,200 monthly deduction reduces take-home pay, while simultaneously increasing PF savings. The employer therefore needs to communicate the change clearly rather than allowing employees to discover a lower net salary from their payslip.
At Team IN Filing, we recommend calculating this impact employee-wise before implementation. A payroll review can show management the additional monthly cost, annual cost, employee deduction and revised take-home before the revised PF treatment is implemented.
Can Companies Restructure Salary to Manage the Higher PF Cost?
Yes, compensation can be reviewed — but it must be done lawfully. The September 2026 PF change is a good time for employers to examine whether the existing Basic Pay, DA and allowance structure is still appropriate under the Labour Code wage framework.
The important rule is simple: do not reduce Basic Pay artificially just to avoid PF. Under the Code on Wages, specified excluded components are subject to the 50% mechanism, and excess amounts can be added back into wages for statutory purposes.
Therefore, a proper salary review should start with CTC → statutory wages → PF applicability → contribution → employee take-home. Only after this calculation should the company consider whether its compensation structure needs adjustment.
Team IN Filing approach: We review the employee-wise salary structure, apply the wage-definition rules, identify employees affected by the revised ₹25,000 ceiling and calculate the additional employer cost before recommending any compensation restructuring.
PF ₹25,000 Limit – Employer FAQs
1. If Basic Salary is ₹40,000, will PF automatically become ₹3,000 on ₹25,000?
Not automatically. A ₹40,000 Basic Salary employee cannot simply be assumed to have a mandatory PF contribution of ₹3,000. The employee’s existing PF membership/UAN status, date of membership and applicable statutory provisions must first be checked. If the employee is already a PF member and the applicable contribution is restricted to the statutory ceiling, the revised treatment needs to be determined under the new framework rather than applying ₹25,000 mechanically.
2. What if the employee’s Basic + DA is ₹20,000?
If the employee is covered under the applicable PF provisions and the relevant PF wage is ₹20,000, the revised ₹25,000 ceiling does not require contribution on ₹25,000. The relevant wage would be ₹20,000, subject to the applicable statutory rules. At 12%, the employee contribution would mathematically be ₹2,400.
3. If an employee’s gross salary is ₹40,000, is Basic automatically ₹20,000?
No. ₹20,000 is only a simple illustration of 50% of ₹40,000. The Labour Code’s wage definition and 50% mechanism must be applied to the actual remuneration components. The Ministry’s FAQ explains that where specified allowances exceed the permitted 50% threshold, the excess is added back to wages.
4. What if Basic + DA is ₹25,000?
Where the employee is subject to mandatory PF coverage and the applicable PF wage is ₹25,000, the revised ceiling can become directly relevant. At a 12% employee contribution, the mathematical contribution on ₹25,000 is ₹3,000 per month, subject to the applicable PF provisions and contribution structure.
5. Does every employee earning above ₹25,000 stop being covered by PF?
No. The ₹25,000 figure is the revised wage ceiling for mandatory coverage; it is not a rule that employees earning above ₹25,000 can never be PF members. Existing membership and the applicable EPF provisions must be examined before deciding the employee’s treatment.
6. Does the new notification mean every employee’s PF wage is now ₹25,000?
No. ₹25,000 is the revised statutory ceiling for the relevant mandatory-coverage framework. An employee whose applicable PF wage is ₹20,000 does not become a ₹25,000 PF-wage employee merely because the ceiling has increased.
7. Can the company reduce Basic Pay and increase allowances to reduce PF?
A company can review and redesign its compensation structure, but it should not use artificial salary splitting simply to defeat statutory wage requirements. The 50% mechanism can bring excess specified allowances back into wages for statutory calculations.
8. What should an employer do before the next PF filing?
Review the employee master, Basic + DA, allowances, statutory wage calculation, PF membership, employer contribution and ECR. Employees falling between the old ₹15,000 ceiling and the new ₹25,000 ceiling deserve particular attention because the Government has identified this as the key expanded coverage group.
Existing PF Members vs Newly Covered Employees: What Should HR Check?
The revised ₹25,000 ceiling does not mean that every employee should be treated identically. HR should first separate employees into existing PF members, employees who may now become mandatorily covered, and employees already contributing on higher wages.
| Employee position | What HR should do |
|---|---|
| Existing PF member | Review existing contribution basis and applicable ceiling. |
| Relevant wages ₹15K–₹25K | Check whether the revised mandatory coverage now applies. |
| Relevant wages above ₹25K | Check PF membership and applicable statutory provisions; do not assume automatic exclusion. |
The Government has specifically identified employees drawing wages between ₹15,000 and ₹25,000 as the principal group affected by the expanded coverage.
PF ₹25,000 Limit: What Should HR and Payroll Change?
Do not change the PF setting across the entire payroll first and investigate later. A safer process is to review the employee data first and update payroll second.
7-step payroll check:
1. Identify employees around the old ₹15,000 ceiling.
2. Check Basic Pay + DA and applicable wage components.
3. Apply the relevant wage-definition and 50% mechanism.
4. Verify UAN and PF membership status.
5. Calculate employee and employer contribution.
6. Update payroll and employee communication.
7. Reconcile payroll with ECR before filing.
EPFO’s implementation communication specifically requires employers to be informed about the enhanced wage ceiling and its revised contribution obligations.
What Is the Risk of Ignoring the New PF Ceiling?
The risk is not limited to a wrong payroll figure. If an employee who should be covered is omitted or the contribution is incorrectly calculated, the employer may subsequently face short-payment, arrears, interest, damages and EPFO compliance proceedings under the provisions applicable to the relevant period.
The 17 September 2026 Gazette notification does not itself introduce a new penalty or interest rate. The financial consequences of delayed or short payment arise under the applicable social-security and EPF provisions. Employers should therefore not wait for an EPFO notice before reconciling the revised payroll position.
Simple rule: Correct PF calculation before filing is cheaper and easier than reconstructing several months of payroll after an EPFO query.
Practical PF Review: What We Would Check for a Bangalore Company
Consider a Bangalore technology company with 50 employees, including several employees whose monthly remuneration is between ₹30,000 and ₹50,000. Some have PF, while others were previously outside mandatory coverage based on the old wage ceiling.
Instead of applying ₹25,000 across the payroll, the first step is an employee-wise wage and PF mapping. We would review Basic Pay, DA, applicable allowances, the 50% wage mechanism, UAN status and previous ECR records.
The company can then see exactly which employees are affected, what the additional employer cost may be, how employee take-home changes and whether the existing CTC structure requires lawful restructuring.
This approach is particularly useful for Bangalore MSMEs and growing IT, startup, consultancy and service companies where salary structures are frequently revised as employees receive increments and promotions.
₹25,000 PF Limit: What It Does NOT Mean
It does NOT mean:
✘ Every employee must have ₹25,000 as Basic Pay.
✘ Every employee’s PF contribution automatically becomes ₹3,000.
✘ Every employee earning above ₹25,000 is automatically outside PF.
✘ Gross salary is automatically the same as PF wages.
✘ A company can simply rename Basic Pay as allowances to avoid PF.
What it does mean:
✓ The Chapter III wage ceiling has increased to ₹25,000.
✓ More employees may now come within mandatory EPFO coverage.
✓ The employee-wise wage position needs review.
✓ The Labour Code wage-definition and 50% mechanism matter.
✓ Employer cost and employee take-home may change.
✓ Payroll and ECR should reflect the applicable position.
PF ₹25,000 Compliance Checklist for Employers
Before the next applicable PF filing, management and payroll should complete this quick review:
- Identify employees in the ₹15,000–₹25,000 range.
- Check Basic Pay, DA and other relevant wage components.
- Apply the applicable 50% wage mechanism.
- Verify UAN and existing PF membership.
- Calculate employee and employer contribution.
- Assess the effect on employee take-home pay.
- Calculate the additional annual employment cost.
- Update payroll wherever required.
- Reconcile payroll data with ECR and challan.
- Maintain an employee-wise working paper for future verification.
PF Limit ₹25,000 – Frequently Asked Questions
Is the PF wage ceiling really increased from ₹15,000 to ₹25,000?
Yes. The Government’s Gazette Notification S.O. 5109(E), dated 17 September 2026, notifies ₹25,000 per month as the wage ceiling for Chapter III of the Code on Social Security, 2020, effective from the date of Gazette publication.
Will every employee now contribute PF on ₹25,000?
No. ₹25,000 is the notified wage ceiling for the relevant mandatory-coverage framework. The employee’s actual statutory wage, PF membership and applicable contribution provisions must first be determined.
If Basic + DA is ₹20,000, will PF be calculated on ₹20,000?
Where the employee is covered and ₹20,000 is the applicable PF wage, the ₹25,000 ceiling does not require PF to be calculated on ₹25,000. At a 12% rate, the mathematical employee contribution on ₹20,000 is ₹2,400, subject to the applicable statutory provisions.
If Basic Salary is ₹40,000, does PF automatically become ₹3,000?
Not automatically. The employer must check the employee’s PF membership, applicable wage and contribution provisions. The ₹25,000 ceiling should not be mechanically applied to every employee with Basic Salary above ₹25,000.
If gross salary is ₹40,000, is Basic automatically ₹20,000?
No. ₹20,000 is only 50% of ₹40,000 and is not automatically the employee’s statutory wage. The actual remuneration components and the applicable wage-definition rules must be examined.
Can the company increase allowances and reduce Basic Pay to control PF cost?
A company can review its compensation structure, but it should not artificially split wages merely to defeat statutory requirements. The applicable 50% mechanism may bring excess specified excluded components back into wages.
Will the new PF rule increase employee take-home salary?
Where an employee’s PF contribution increases, the immediate effect can be a reduction in monthly take-home pay, while the employee’s PF savings increase. The actual impact should be calculated employee-wise.
Will the new PF rule increase the company’s cost?
For employees whose applicable contribution base increases or who newly become subject to mandatory coverage, the employer may have an additional recurring statutory cost. The exact amount depends on the employee’s applicable wage and PF treatment.
What should an employer do before filing the next PF return?
Complete an employee-wise review of wages, PF eligibility, UAN status, contribution, payroll and ECR. Do not wait for an EPFO query to identify a mismatch.
Need Help Implementing the ₹25,000 PF Change?
For employers, the difficult part is not knowing that the ceiling has changed. The difficult part is determining which employees are affected and what the correct payroll treatment should be.
Team IN Filing provides PF and labour-law compliance support in Bangalore, including employee-wise wage review, PF applicability, compensation-structure review, payroll reconciliation, ECR verification and ongoing statutory compliance.
Our objective: Help the employer understand the additional PF cost, protect employee take-home clarity, review the compensation structure and implement the revised PF requirement correctly — without using artificial salary splitting or creating avoidable labour-law risk.
Team IN Filing – CA, CS & Labour Compliance Support
Sahakar Nagar, Bangalore – 560092
Email: team@teamindia.co.in
Phone: 7019827351
Author: Damodharaa R
CA, CS and Legal Advisor | 20+ Years of Professional Experience
This article has been prepared for employers and HR/payroll professionals based on the Government of India’s Gazette Notification dated 17 Sept 2026 and related official EPFO/Ministry communications. The legal position should be reviewed against the provisions and EPFO instructions applicable to the relevant contribution period.
Free PF ECR Template – Updated for ₹25,000 Wage Ceiling
Preparing the next PF ECR? HR and payroll teams can use our free ECR template to prepare and review employee-wise PF data following the PF wage ceiling change from ₹15,000 to ₹25,000.
For HR, Payroll & Accounts Teams | Always verify the final ECR against applicable EPFO requirements before filing.